Who finances cannabis equipment?
The financing source depends on the asset, borrower, jurisdiction, operating history, site, and repayment plan. Equipment lessors focus on identifiable machinery and expected resale value. Specialty lenders may combine equipment collateral with guarantees and operating cash flow. Vendors and sellers may offer installments or milestone terms. Real estate lenders or sale-leaseback investors can fund building improvements or release property equity. Private credit and equity may cover construction or working capital that equipment debt does not fit.
State licensing does not automatically create federal program eligibility. FinCEN's marijuana-banking guidance explains the enhanced diligence financial institutions apply. SBA eligibility must be confirmed under current federal rules and the applicant's complete business structure. Do not assume an ordinary SBA product is available to a marijuana business.
Lease, loan, sale-leaseback, and vendor terms compared
| Structure | Best fit | Ownership and collateral | Cash-flow logic | Questions to resolve |
|---|---|---|---|---|
| Equipment lease | New or used movable machinery with a financeable useful life | Lessor owns the asset during the lease; guarantees or additional support may apply | Deposit and scheduled rent preserve more initial cash than a purchase | End-of-term option, early payoff, taxes, insurance, return condition, and lien release |
| Equipment loan | Borrower wants ownership from closing | Borrower owns the asset; lender records a security interest | Down payment plus principal and interest over the useful-life window | Advance rate, amortization, maturity, fees, covenants, guarantees, and prepayment |
| Sale-leaseback | Operating company already owns equipment or real estate and needs liquidity | Investor buys the asset and leases it back | Converts existing equity into cash while creating a continuing rent obligation | Valuation, rent escalators, purchase option, maintenance, relocation, and default remedies |
| Vendor or seller terms | Defined purchase from one manufacturer, dealer, or asset owner | Contract may retain title or a security interest until payment | Payments follow deposit, fabrication, shipment, installation, or acceptance milestones | Refundability, factory acceptance, final payment, warranty, service, and failure remedies |
Compare total dollars paid and net cash received, not the stated rate alone. Include deposits, original-issue discount, closing and legal fees, taxes, insurance, end-of-term price, minimum interest, warrants, and early-payoff cost.
What operators should prepare before requesting terms
- Transaction summary: requested amount, exact use, borrower entity, site, license status, opening date, and repayment source.
- Sources and uses: equipment, construction, installation, tax, freight, professional fees, contingency, working capital, owner equity, and other capital.
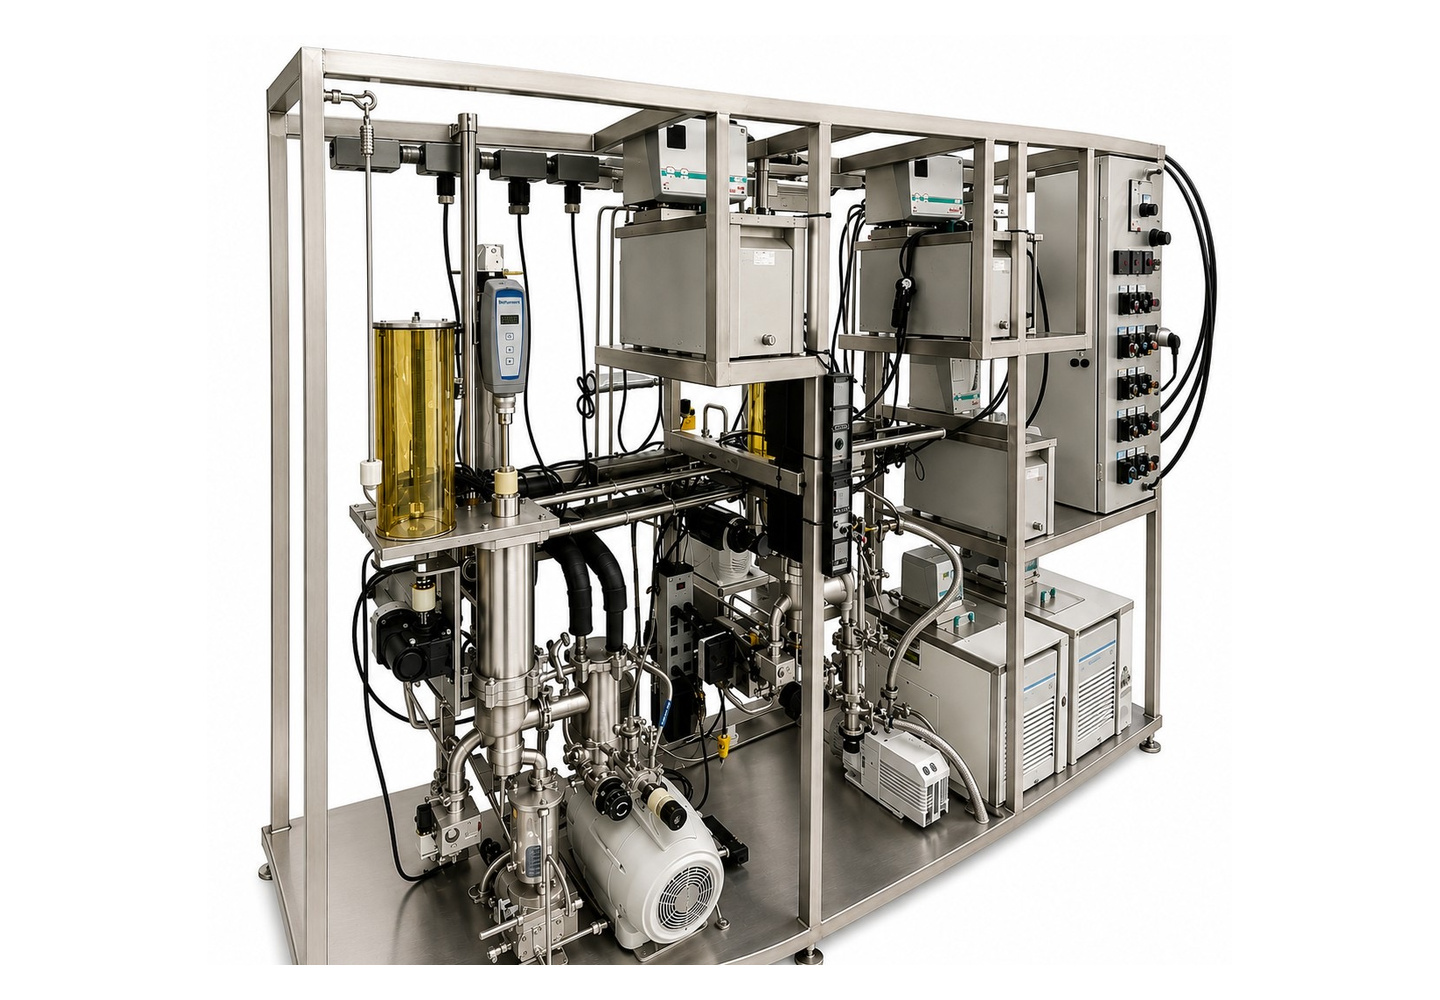
- Equipment schedule: manufacturer, model, serial number when available, quantity, price, condition, location, utilities, lead time, warranty, and acceptance criteria.
- Vendor evidence: dated quotes, purchase agreements, deposits, general-arrangement drawings, performance specification, and payment milestones.
- Facility evidence: site control, zoning, design status, permits, utility path, contractor budget, equipment access, and commissioning schedule.
- Financial package: historical financials and tax returns when available, bank statements, debt schedule, thirteen-week cash forecast, monthly model, and downside case.
- Legal and compliance file: entity documents, ownership, licenses, conditions, renewals, insurance, liens, litigation, and material contracts.
Use the broader cannabis business financing guide when the request also includes real estate, construction, working capital, private credit, or equity.
How lenders evaluate equipment condition
New equipment is easier to identify when the quote, manufacturer warranty, documentation, and factory test are current. Used equipment can still be financed when the file establishes identity, ownership, condition, serviceability, remaining life, removal cost, installation cost, and resale support.
| Evidence | Why it matters | Minimum useful record |
|---|---|---|
| Identity and title | Confirms the lender can identify and perfect an interest in the asset | Manufacturer, model, serial plate, seller, invoice, lien search |
| Condition | Supports useful life and repair assumptions | Inspection report, photos, powered test, faults, wear, missing parts |
| Performance | Shows the asset can perform the intended process | Representative acceptance protocol, inputs, outputs, settings, raw results |
| Documentation | Supports installation, operation, maintenance, and resale | Manuals, drawings, software rights, service history, certification records where applicable |
| Removal and installation | Determines total landed cost and collateral value | Rigging, freight, utilities, room work, startup, training, commissioning |
| Parts and service | Limits downtime and obsolescence risk | Current support contact, critical-spares list, component availability |
The used extraction equipment inspection guide covers technical diligence. The new-versus-used decision guide compares procurement paths, while the equipment resale FAQ covers seller records and transaction preparation.
Lease versus buy decision
Leasing can reduce the initial cash requirement and align payments with useful life. Buying can provide ownership, depreciation, and control over disposition. Neither is automatically cheaper. Model the complete payment schedule, tax treatment with a qualified adviser, end-of-term value, service, obsolescence, expected holding period, and the cost of cash tied up in the asset.
- Lease when preserving opening cash has more value than early ownership and the return or purchase terms are acceptable.
- Buy when the asset has a long supported life, the facility expects to use it through that life, and ownership fits the capital plan.
- Delay when the process, throughput, utilities, site, acceptance test, or license path is still unresolved.
Lender and lessor red flags
- A rate quoted without fees, discount, legal costs, taxes, insurance, or end-of-term payment.
- Payment due before factory acceptance, shipment verification, or document delivery.
- Cross-collateralization of unrelated assets without a release mechanism.
- Daily or weekly payments that do not match the operating cash cycle.
- Milestones controlled by a utility, regulator, landlord, or contractor but treated as borrower defaults.
- Undefined equipment, missing serial numbers, unsupported condition claims, or no removal plan.
- Blanket guarantees, confession-of-judgment language, or default remedies that counsel has not reviewed.
- No written procedure for payoff, lien release, assignment, asset sale, or insurance proceeds.
Financing a new facility versus an operating facility
A new facility is financed against milestones because repayment depends on future operations. Connect permit release, utility service, construction completion, equipment delivery, commissioning, inspection, first production, first sale, and cash break-even. Fund schedule contingency and opening liquidity rather than shrinking working capital to close a sources-and-uses gap.
An operating facility provides evidence: production records, bank activity, sales, margins, compliance history, maintenance, and inventory. An expansion request should identify the measured bottleneck, the equipment that removes it, the incremental accepted output, and the cash effect under a downside case.
The Virginia equipment procurement checklist is one example of connecting license timing, equipment specification, facility interfaces, and finance preparation.
Frequently asked questions
Can cannabis equipment be leased?
Yes, when a lessor accepts the borrower, jurisdiction, asset, use, collateral profile, and repayment plan. Availability and terms vary. Request a complete dated proposal for the actual transaction.
Can used cannabis equipment be financed?
Yes, when identity, ownership, condition, remaining life, installation, parts, service, and resale support are documented to the capital provider's satisfaction.
Can hemp equipment qualify for ordinary financing?
Hemp-related eligibility depends on the borrower, products, legal compliance, affiliates, lender policy, and current federal and state rules. Do not assume the word hemp determines eligibility. Confirm with the lender and qualified counsel.
Is an equipment lease always better for cash flow?
No. Deposits, advance rent, fees, taxes, end-of-term options, maintenance, insurance, and guarantees determine the actual cash profile.
Does Urth & Fyre provide financing?
No. Urth & Fyre prepares equipment quotes, schedules, condition evidence, sourcing options, and acceptance criteria that operators can present to independent lenders or lessors.
Prepare a financing-ready equipment request
Send the process, product, peak and annual throughput, site, license status, equipment requirement, budget, preferred timing, and new-or-used preference. Request an equipment quote with a financing-ready schedule and condition documentation.